850

·
09-01
Why SLB’s $4.1 Billion Cooling Deal Changes Its Identity Faster Than Its Risk Profile
$SLB Ltd(SLB)$’s acquisition of Kelvion is a deliberate move away from dependence on oilfield activity and toward the thermal infrastructure required by artificial-intelligence data centres. The market rewarded the strategy, but the purchase introduces acquisition and execution risks when enthusiasm for AI infrastructure is already high. SLB announced on August 31 that it would acquire Kelvion for $4.1 billion, comprising $3.4 billion of cash and $700 million of assumed debt. The transaction is expected to close in the first half of 2027. Kelvion makes heat exchangers and cooling systems for data centres, heat pumps, carbon capture and industrial applications. Reuters’ August 31 report provides the consideration, timetable and strategic rationale.
TOPJackPowell: Above 60.50 matters, but RSI is already stretched. I care more about a clean 58 retest than the first breakout pop.
970

·
09-01
🌟 $Circle Internet Corp.(CRCL)$ dramatic 9.65% intraday surge to USD 95.55 was countered by a 2.79% to USD 92.88. This was due to a classic bout of near term institutional profit taking & multiple compression ahead of critical macroeconomic catalysts rather than a breakdown of its core business fundamentals. I believe the single biggest reason for the 2.79% drop is institutional de-risking ahead of this Friday's highly anticipated August Non Farm Payrolls report. Asset managers are trimming tech linked winners to build up cash reserves, refusing to carry over-leveraged long positions into a major economic release. Circle is also sensitive to short term US Treasuries backing the USDC too. The reality is the recent rebound is built
TOPI don't buy the payrolls-only explanation. The bigger risk is USDC reserve duration getting repriced if short-end yields stay jumpy.
987
·
09-01
🌟🌟Before you panic dump $NVIDIA(NVDA)$ shares to chase young upstart competitors like $Marvell Technology(MRVL)$ let's look closely at the battlefield defenses. A minor pre market dip changes none of Nvidia's advantages. NVIDIA don't sell chips alone anymore. They sell ecosystems. Competitors can build faster chips but they cannot easily replicate CUDA. Millions of developers are anchored to Nvidia's software architecture. Trying to move a massive enterprise AI model from CUDA to a competitor is a coding nightmare. NVIDIA rolls out its next generation silicon roadmaps - the Vera Rubin architecture well ahead of its competitors. Whether NVIDIA moves up or down in the short term,
TOPThe moat is deeper than CUDA alone. DGX plus the AI Enterprise stack is what really locks in enterprise customers, and Rubin keeps that lead from looking temporary
739
·
09-01
🌟The 5% leap across the memory titans proves that the global computing architecture cannot scale without advanced hardware packaging. The memory supercycle is no longer a short term trading fad. It is the physical foundation of the next decade's computing infrastructure. Which memory stock to get on the bus? I choose $SK hynix(SKHY)$ the reigning HBM King as they command the global market share for the current generation HBM3 and HBM3E silicon architectures. A big catalyst for Hynix was its recent massive USD 4 billion advanced packaging powerhouse in Indiana, USA. This was backed by substantial US Chips Act grants. SK Hynix is the cutting edge of AI packaging. It is also
TOPSold out through 2027 sounds strong, but capex durability matters more. If GPU demand is already slowing, memory orders won’t stay immune for long
1.46K
·
09-01
SanDisk +5.5%: Real Breakout or Just MSCI Buying?
$SanDisk Corp.(SNDK)$ $Micron Technology(MU)$
TOPClosing ramp was mostly index flow, but day-two tape matters more. If SNDK holds gains after MSCI demand is gone, that says way more than Monday's 5.5%
62.93K
·
09-01
$CAT Ends 5-Wave Cycle From April 2025 as 7-Swing Correction Targets Blue Box
In this Elliott Wave update, we examine the latest structure in Caterpillar Inc. ($CAT). The stock completed a powerful 5-wave advance from the April 2025 low, which ended the bullish cycle into the 2026 peak. Since then, price has turned lower and is now correcting that entire advance. 5 Wave Impulse + 7 Swing WXY correction $NVDA The current decline is expected to unfold in a 7-swing W-X-Y structure. Therefore, although temporary rebounds can occur along the way, the correction likely needs additional downside before the next major bullish opportunity develops. The key area to watch comes at the 640.56–458.44 Blue Box Area, where buyers are expected to enter and the next long opportun
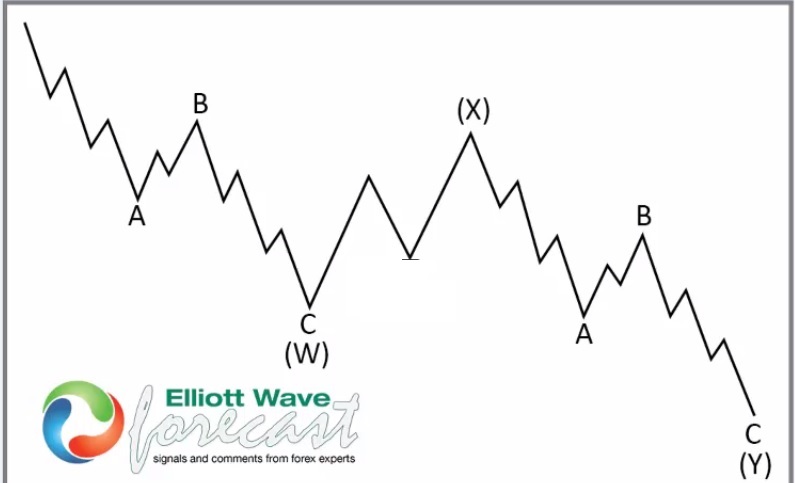
TOPIf this is really a larger ABC instead, that Blue Box may not be the finish. I care more about whether 267.30 still anchors the higher degree count.
62.76K
·
09-01
Tesla ($TSLA): Why the Elliott Wave Nesting Structure Can Open the Door to $937 Within the Next Five Years
Tesla has spent the last several years moving through what, on the surface, can look like a frustrating period of volatility and consolidation. From an Elliott Wave perspective, however, that volatility may be serving a much more important purpose: building a series of nested first and second waves that can eventually produce a powerful third-wave acceleration. Our long-term view on $TSLA remains constructive. The weekly structure suggests that the major advance from the 2023 low is not necessarily the end of the bullish sequence. Instead, we believe Tesla may be developing a nest inside a larger bullish cycle, and that structure can ultimately open the door to the $937 area within the next five years. The important point is that $937 should not be viewed as a conventional fundamental pric
TOPFive years sounds fair, but I’d watch year three the closest. That’s usually where nested third waves start syncing and the move stops feeling like noise.
62.78K
·
09-01
XAGUSD – Turns Higher After Hitting Extreme Area
Hello Traders, in today’s blog we’re reviewing the $XAGUSD wave count shared with members, which highlighted a strong bullish outlook. The Elliott Wave pattern confirmed the move right at the extreme/high‑frequency zone, propelling prices sharply higher. XAGUSD After Completing Major Correction from All‑Time Highs Silver peaked earlier this year at 121.503 on January 29, 2026, before entering a six‑month corrective phase that concluded at 3940.68 on July 17, 2026. From that low, Silver rallied to complete wave (4) at 62.548, then turned higher, finishing wave 1 of a new nest. Price has since pulled back in a proposed wave 2, holding against the 62.548 pivot. The Forecast: Completion of Wave ((iv)) Correction The setup identified Silver at a decisive turning point following a corrective pul
TOPI lean bearish here: 62.548 still looks like the level that eventually gives way, and calling the major correction done after just half a year off the high feels early
1.30K
·
09-02
$CNMC Goldmine(5TP.SI)$ 2 Target Price CNMC is a pure-play gold producer operating the Sokor gold field in Kelantan, Malaysia. --Growth Catalysts for CNMC Goldmine(5TP.SI)-- 1. Expanded Production Capacity CIL Plant upgrade completed in April 2025: Daily processing capacity nearly doubled from 500 tonnes to 800 tonnes per day. Gold output from the CIL plant jumped 65% in 2H2025 vs 2H2024. CNMC Goldmine earnings growth came from "diversification into base metals production and the expansion of the gold processing capacity, not simply from rising gold prices. 2. Underground Development & Higher-Grade Ore Discovery New underground facility under construction at Sokor. Two new vertical shafts budgeted at US$12M
TOP500 to 800 tpd is the part that matters, and 65% output growth says execution is real, not just gold doing the heavy lifting
1.17K
·
09-02
Options puppy beginners guide 🚀 Broadcom Reports Tonight: The Beginner’s Guide to AI Earnings Season — Why I Hold Broadcom, Dell & Apple Tiger Brokers | Market Rebound: Rally or Pullback? Capture potential opportunities. Stay Flexible with Options
🌪️ A Big Week for Technology Stocks If you own technology stocks right now, this is the week that teaches you how the game is played. 📚📈 On Tuesday, September 1, Wall Street had one of its worst sessions in weeks. Oil jumped above $90 a barrel following fresh U.S. strikes on Iran, Treasury yields climbed to their highest levels since early 2025, and the Nasdaq fell around 1%. 🛢️📉 Then came Dell Technologies. After the market closed, Dell reported quarterly results, and the stock jumped around 8% in after-hours trading. 💻🚀 Tonight, the spotlight turns to Broadcom. After the U.S. market closes on Wednesday, September 2 — roughly 4 a.m. Thursday Singapore time — Broadcom will report its fiscal Q3 results. The big question is: 🤖 Can Broadcom Really Triple Its AI Business? ⸻ 📚 First: A 5-Minute
TOPBeta risk across the whole AI stack still looks underpriced to me. With yields this sticky, Broadcom Dell and Apple can all report fine and still get de-rated fast
1.00K
·
09-02
I’m bullish on $Broadcom(AVGO)$ after earnings, with my pick around the $350–$400 area. I’m expecting solid AI revenue growth and potentially stronger guidance, especially as AI infrastructure spending remains strong across GPUs, networking and custom silicon. The custom AI chip opportunity is what excites me most. I don’t expect Broadcom to replace NVDA anytime soon, but more AI companies building chips tailored to their own workloads could become a major growth driver for Broadcom. If management provides clearer visibility on OpenAI and other custom-chip programs, I think the market could reward AVGO with another leg higher. At the same time, I’ll be cautious if guidance fails to match the market’s already-high expectations. That said, expectat
TOPAI spend looks strong now, but enterprise IT budgets do not stretch forever. If guidance is only clean instead of huge, this multiple can crack fast
764
·
09-02
I think Monday’s pullback is more of a warning sign than a reason to turn bearish. Higher oil prices, rising Treasury yields and renewed U.S.-Iran tensions are uncomfortable, especially for high-valuation growth stocks, but the major indexes still finished August higher. For me, the biggest concern is whether $United States Oil Fund LP(USO)$ oil staying above $90 will create more persistent inflation pressure. If yields continue rising, tech and AI valuations could face more pressure, while companies like $Marvell Technology(MRVL)$ show that investors increasingly want AI demand to translate into real revenue and earnin
TOPEIA draw was the bigger tell last week. With Iran risk still bid into crude, USO above 90 keeps the inflation scare alive and makes September way trickier for growth 📈
1K
·
09-02
I think the AI hardware trade is clearly broadening beyond GPUs. $NVIDIA(NVDA)$ may still dominate compute, but HBM, enterprise SSDs and networking are becoming increasingly important. That makes $Broadcom(AVGO)$ interesting because it can benefit from both custom ASICs and networking. I’m watching AVGO’s earnings closely because another strong AI outlook would reinforce the idea that AI CapEx is spreading across the ecosystem. I don’t see Broadcom replacing NVIDIA; rather, GPU + ASIC + networking could become the winning combination as hyperscalers optimize performance, power and cost. For me, the biggest question is valuation, not demand. If Broadcom delivers another blowout quarter but the stock str
TOPAI CapEx broadening makes sense, but 40x forward earnings may already price in most of the optimism. If AVGO beats and still stalls, that probably tells the whole story
604
·
09-02
I think the memory story is still fundamentally strong, but I’m becoming more selective at these valuations. DRAM supply looks structurally tight, while HBM continues absorbing capacity due to strong AI demand. That gives $Micron Technology(MU)$ and $SK hynix(SKHY)$ a stronger setup into 2027, in my view. I’m also paying close attention to how companies use their cash. SK hynix’s huge buyback is a strong confidence signal, while Micron’s heavy reinvestment suggests management still sees attractive long-term demand. Buybacks aren’t a guaranteed price floor, but they show these companies are generating serious cash. The biggest risk is that ~85% gross margins create very high expectations. I’ll be watching D
TOPHBM capacity pull is the part I care about most here. If that stays tight, DRAM pricing probably has more room than people think
24.14K
·
09-02
AJJ 1H2026: Healthcare Products Before AI Robotics
$AJJ Medtech(584.SI)$ Before reading AJJ Medtech Holdings Limited (SGX:584) only through the AI robotics angle, it may be more useful to first look at its healthcare products and services revenue base. In 1H2026, AJJ reported total revenue of about S$1.219m. Of this, healthcare products and services contributed about S$1.086m, or around 89.1% of total revenue. This matters because healthcare distribution is not just about selling products. It can provide customer access, procurement experience, product catalogue depth, regulatory familiarity and supply-chain execution. AJJ’s disclosed product areas include medical products, laboratory products / IVD and life sciences, and animal health / VetCare solutions. The key question is whethe
TOP89.1% from healthcare is meaningful, but inventory turnover is still the cleaner proof point here
1.41K
·
09-02
Stock to watch - Abbvie
$AbbVie(ABBV)$ is a leading global biopharmaceutical company based in the United States. Ranked among the largest in the industry, it develops treatments across key areas including immunology, cancer, neurology, and aesthetics. Its major products include blockbuster medicines like Humira, Skyrizi, and Rinvoq for autoimmune conditions, cancer therapies like Imbruvica and Venclexta, mental health medication Vraylar, and Botox. The name "AbbVie" originates from a combination of "Abbott," the name of its former parent company, and "vie," which refers to a Latin root meaning 'life.' In a long-term uptrend, but it is currently hitting a strong price ceiling at $260–$262. Momentum is slowing down, which suggests sellers are stepping in and could cause
TOPThat 260 breakout setup ignores the real risk: Humira erosion can still drag guidance, so I would not treat resistance as the only variable.
657
·
09-02
🌟🌟🌟 Monday's pullback is a classic short term volatility spike rather than a permanent threat to the AI rally. This is because hyperscale AI capital expenditure is an unyielding structural mandate that mega cap balance sheets will continue to fund, completely regardless of short term oil spikes or bond market volatility. Hyperscalers like Microsoft, Alphabet, Meta and Amazon aren't spending billions on custom ASICs and HBM because it is a fun hobby. They are doing it because failing to secure a piece of the next generation computing infrastructure may mean tech obsolescence. So stay cool, stay invested because investing is a marathon, not a sprint. @Tiger_comments @Tiger
TOPAI capex is real, but if rates and oil stay sticky the whole tape can de-risk fast. That can still slow the multiple even if the buildout stays on
1.53K
·
09-02
Broadcom's Custom Silicon Surge vs. NVIDIA's GPU Hegemony: Portfolio Allocation in the Next Era of AI Infrastructure
$Broadcom(AVGO)$ Broadcom’s massive 143% surge in AI-related revenue represents a fundamental structural pivot in AI infrastructure rather than a transient spike. As hyper-scalers transition from generic model training to specialized execution, custom application-specific integrated circuits (ASICs) and high-speed networking silicon have emerged as central pillars of AI architecture. However, this growth does not signaling the dethroning of NVIDIA. NVIDIA maintains a dominant moat backed by its proprietary CUDA software platform, vertical integration, and full-stack system architectures. Rather than an "either/or" battle, the AI semiconductor market is bifurcating into complementary domains: NVIDIA standardizes off-the-shelf accelerated computing,
TOPI care more about AVGO’s forward multiple here — with software mix in the model, it does not look expensive. NVDA still owns the default stack, but the pair makes sense
700
·
09-02
I would rotate modestly toward cash-flow certainty, not abandon growth. A 10-year yield near 4.8% is more than noise: it raises the discount rate on long-duration AI earnings and makes debt-funded capex increasingly expensive. With oil adding another inflation impulse and September hike odds now around two-thirds, richly valued tech has less room for disappointment. But payrolls are the potential circuit-breaker. A genuinely weak jobs print could pull yields back quickly and revive duration-sensitive tech. So rather than chase the bond selloff, I would favour profitable, cash-generative companies and keep some dry powder. If payrolls surprise stronger, 5% on the 10-year becomes a much more uncomfortable possibility. If they disappoint sharply, today's tech weakness could become the entry p
TOPI agree on favoring cash flow, but rates already reflect a decent chunk of the inflation scare. The bigger question is whether term premium keeps doing the heavy lifting here
890
·
09-02
I would wait for the print rather than front-run it. Broadcom's AI story is clearly real: Q2 AI semiconductor revenue hit $10.8bn, +143% YoY, and management guided Q3 to $16bn. But the market already knows that. The real hurdle is whether those huge orders translate into durable margins and higher FY27 guidance. The heavier AI mix itself is expected to compress gross margin towards 74%, while Broadcom explicitly warns that custom accelerators and AI systems carry lower gross margins. The Google-Marvell threat also looks more medium-term than immediate, with Marvell saying the Google deal becomes much more significant only in FY29. So my trigger is not simply "$16bn AI revenue achieved". I want $16bn+, resilient margins and, most importantly, an upgrade or stronger evidence behind the $100b
TOPGross margin is the swing factor here. AI mix matters, but software mix and operating leverage probably decide whether that FY27 target gets real support.